Inherited IRA RMD Rules: Are You Making a Tax Mistake That Could Cost Thousands?
You’ve inherited an IRA. Great – but do you really know what the IRS expects from you?
Inherited IRA rules, significantly altered by the SECURE Act (2019), govern how beneficiaries must withdraw funds from an IRA received after an owner's death. For most non-spouse beneficiaries, the SECURE Act eliminated the previous "stretch" provision, now requiring the entire inherited IRA account to be fully distributed within 10 years of the original owner's death. Spouse beneficiaries, however, retain more flexible options, including treating the inherited IRA as their own, while certain Eligible Designated Beneficiaries can still stretch distributions over their lifetime.
Most people assume they can leave the account untouched or withdraw as needed. But what if your strategy accidentally triggers penalties or taxes that drain your inheritance faster than you ever imagined?
In this article, we’ll unpack the often-confusing required minimum distribution (RMD) rules for inherited IRAs, especially after the SECURE Act. Whether you’re a spouse, child, or non-family beneficiary, the choices you make today can impact your tax bill for years to come.
Understanding Inherited IRA RMD Rules
What Is an Inherited IRA?
An inherited IRA is exactly what it sounds like: an IRA you receive upon someone’s death. But unlike a regular IRA, you can’t contribute to it – and the IRS has strict rules on how and when you must take money out.
👉 Spouse vs. Non-Spouse Beneficiaries
- Spouse beneficiaries have more flexible options, including treating the account as their own.
- Non-spouse beneficiaries must follow distribution rules based on their relationship to the original owner.
Why Did RMD Rules Change Under the SECURE Act?
Before 2020, non-spouse beneficiaries could “stretch” distributions over their lifetime, minimizing annual taxes.
But with the SECURE Act (2019), Congress ended this strategy for most. Now, non-spouse beneficiaries must deplete the account within 10 years, fundamentally changing the tax planning landscape.
What Were the Key SECURE Act Changes for Inherited IRAs?
| Before SECURE Act | After SECURE Act (2020 onwards) |
|---|---|
| Non-spouse beneficiaries could stretch RMDs over their life expectancy. | Non-spouse beneficiaries must withdraw the entire account within 10 years (with limited exceptions). |
Who Needs to Take RMDs and When?
What Options Do Spouse Beneficiaries Have for Inherited IRAs?
Spouses have unique options:
- Treat as Own IRA – Roll over into their own IRA and delay RMDs until age 73 (or 75, depending on birth year).
- Remain as Beneficiary IRA – Keep as an inherited IRA and take RMDs based on their life expectancy.
👉 Why This Matters: Choosing the wrong option could trigger unnecessary distributions and taxes earlier than required.
Non-Spouse Beneficiaries
What is the 10-Year Rule for Inherited IRAs?
If you’re a non-spouse beneficiary, you generally must fully withdraw the account within 10 years of the original owner’s death.
✅ Important Caveat: Starting in 2025, annual RMDs are required for NEDBs if the decedent died after their RBD, in addition to the account needing full depletion by year 10.
Who Qualifies as an Eligible Designated Beneficiary (EDB) for Inherited IRAs?
Certain beneficiaries can still use the lifetime stretch:
- Surviving spouse
- Minor children (until age of majority – which is age 21, NOT your state’s age of majority)
- Disabled individuals
- Chronically ill individuals
- Individuals <10 years younger than the decedent
👉 Example: A child with disabilities can stretch distributions over their lifetime, reducing annual tax burdens.
Non-Designated Beneficiaries
These include:
- Estates
- Charities
- Certain trusts
What are the Distribution Rules for Inherited IRAs?
- If the owner died before RMD age: Entire account must be distributed within 5 years.
- If the owner died after RMD age: Distributions continue over the decedent’s remaining life expectancy.
The Essential Retirement Readiness Checkup
See how seven critical retirement decisions interact to shape your income, taxes, and long-term security — often in ways most people don’t see until it’s too late. Get clarity on how your retirement decisions work together — not just on paper, but in real life.
Calculating RMDs for Inherited IRAs
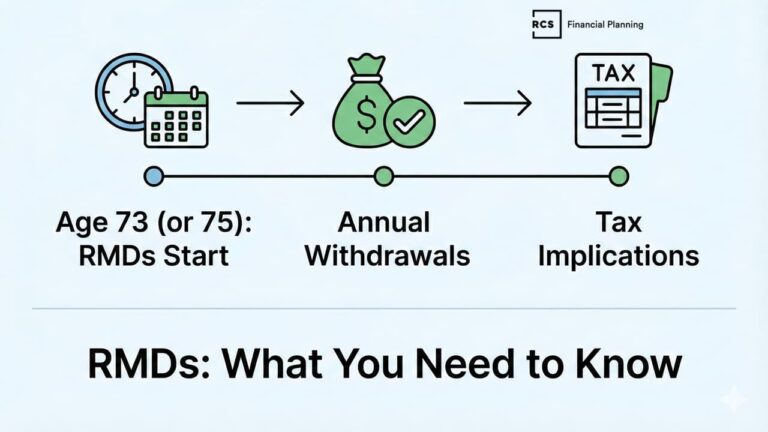
How to Calculate Your RMD
Use the IRS Single Life Expectancy Table:
- Determine your age in the year after inheritance.
- Find your life expectancy factor.
- Divide the prior year-end account balance by this factor.
Can You Provide an Example Calculation for Inherited IRA RMDs?
- Beneficiary Age: 50
- Factor: 34.2
- IRA Balance: $300,000
RMD = $300,000 ÷ 34.2 = $8,772
Source: IRS Publication 590-B
What are Common Mistakes with Inherited IRA RMD Rules?
❌ Failing to take annual RMDs if required.
❌ Waiting until year 10 to withdraw the full amount, triggering massive tax spikes.
❌ Misunderstanding rules for inherited Roth IRAs, assuming RMDs are required.
What Penalties Apply for Missing Inherited IRA RMDs?
Missing an RMD triggers a 25% excise tax penalty, reduced to 10% if corrected promptly (SECURE Act 2.0).
Special Considerations for Inherited Roth IRAs
Non-spouse beneficiaries of inherited Roth IRAs do not have annual RMDs but must fully distribute by December 31 of the 10th year after death. Distributions remain tax-free if the Roth has been open 5+ years.
Planning Strategies to Minimize Taxes
How Can Spreading Inherited IRA Withdrawals Over 10 Years Benefit You?
Most beneficiaries wait until year 10 and face a massive tax bill. Strategic annual withdrawals can:
- Keep you in a lower tax bracket.
- Reduce Medicare IRMAA surcharges.
- Minimize Social Security taxation.
👉 Have you considered how these withdrawals impact your overall retirement income plan?
How Can Roth Conversions Before Death Impact Inherited IRAs?
For original IRA owners, converting to a Roth before death can:
- Avoid forcing heirs to take taxable distributions.
- Leave a tax-free inheritance, though heirs still must distribute within 10 years.
What are the Considerations for Trust Beneficiaries of Inherited IRAs?
The SECURE Act has complicated trust planning:
- Conduit trusts pass RMDs directly to beneficiaries annually.
- Accumulation trusts retain distributions, but funds are taxed at trust tax rates (37% on income over $15,200 in 2025).
👉 Many existing estate plans need updating to align with current law.
What Happens in a Real-Life Scenario When Inherited IRA RMD Rules Are Ignored?
John inherited his uncle’s $400,000 IRA at age 55.
He decided to wait until year 10 to withdraw the full amount. That year, he earned $150,000 from his job. Adding a $400,000 distribution pushed him into the highest tax bracket, costing him over $120,000 in taxes that could have been avoided with strategic annual withdrawals.
👉 What if your current plan is setting you up for the same painful tax surprise?
What are the Key Takeaways Regarding Inherited IRA RMD Rules?
Inherited IRA rules aren’t just bureaucratic red tape – they’re a financial minefield. Most people assume they’re handling these accounts correctly, but the reality is far more complex and unforgiving.
Have you considered whether your inherited IRA strategy is optimized for tax efficiency? Or will your decisions cost you – and your family – more than you realize?
What are the Key Takeaways for Inherited IRA RMD Rules and Planning?
- Inherited IRA rules changed under the SECURE Act.
- Non-spouse beneficiaries generally must deplete the account within 10 years.
- Missing RMDs can trigger hefty penalties.
- Spouse beneficiaries have flexible options requiring careful evaluation.
- Strategic withdrawals and planning can save thousands in taxes.
Ready for clarity and confidence in your retirement plan?
This material is provided for educational, general information, and illustration purposes only. You should always consult a financial, tax, or legal professional familiar with your unique circumstances before making any financial decisions. Nothing contained in the material constitutes tax advice, a recommendation for the purchase or sale of any security, or investment advisory services. This content is published by an SEC-registered investment adviser (RIA) and is intended to comply with Rule 206(4)-1 under the Investment Advisers Act of 1940. No statement in this article should be construed as an offer to buy or sell any security or digital asset. Past performance is not indicative of future results.